
The best lenders for IT contractors use day rate annualisation rather than relying solely on company accounts or salary. Different lenders apply different criteria, so choosing the right lender can significantly increase borrowing potential.
The best lenders calculate income using your current contract day rate multiplied by working days and weeks, reflecting your true earning capacity.
Halifax, NatWest, Accord, Coventry, Skipton, Saffron, Aldermore and Hodge Bank all have established contractor assessment policies.
Each lender applies different rules regarding minimum day rates, contract history and acceptable gaps between contracts.
Many specialist lenders assess affordability using the gross contract value rather than PAYE take-home income.
Most IT contractor-friendly lenders prefer to see twelve to twenty-four months of contracting history in the same technology sector. However, for IT professionals moving from permanent employment into contracting, some lenders including Aldermore and Bank of Ireland Bespoke will consider day-one contractor applications where you can demonstrate a strong technology background and a reputable first client.
Contract length matters too. A rolling monthly contract at a well-known technology firm is viewed more favourably than a short fixed-term contract with an unknown agency, even if the day rates are similar. We advise on how to frame your contract history in the most favourable way and which lenders are most pragmatic about shorter contracts.
IR35 status plays a major role in how lenders assess affordability. The right lender can make a substantial difference to the amount you can borrow.
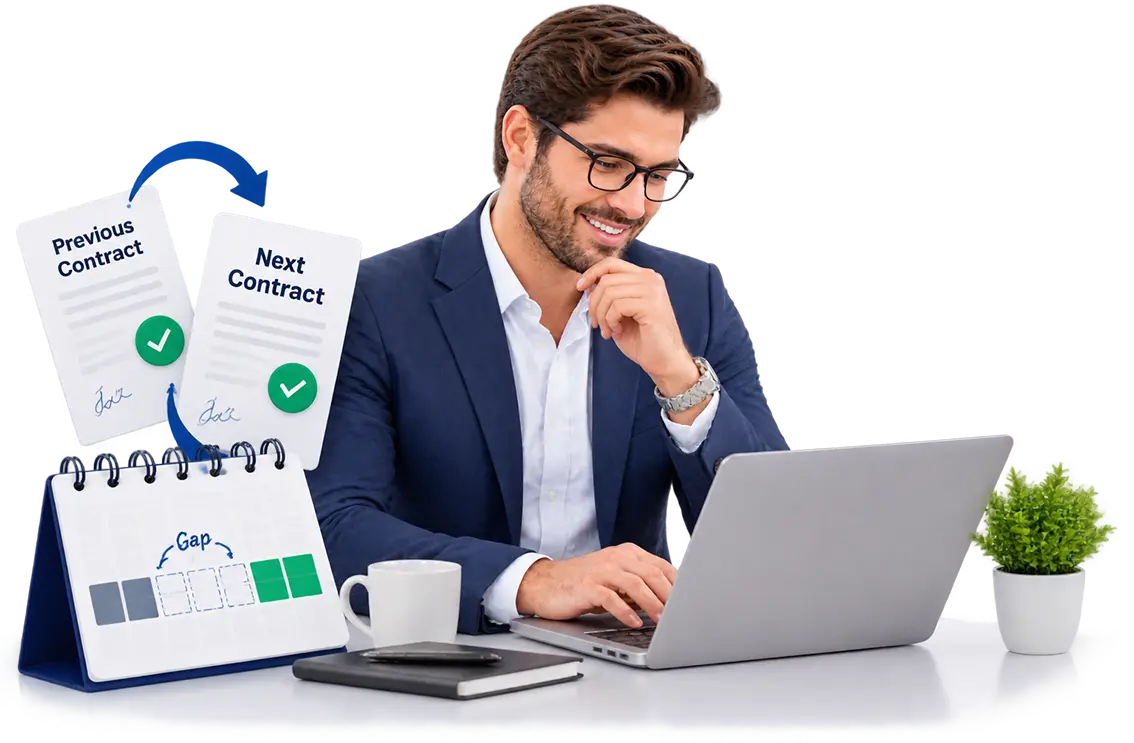
Short gaps (4-6 weeks) between contracts are normal and accepted by specialist contractor lenders. Longer gaps may need a brief explanation but won't disqualify you, especially if you have a current contract when applying.
If you're between contracts, some lenders will proceed based on your most recent contract plus a confirmed next contract, or a track record of short gaps between engagements. We assess your contract history and match you with the right lender.
Senior IT contractors architects, programme directors, CTOs, security specialists on day rates of £700 to £1,500 or more can access some of the largest contractor mortgages available in the UK market. At 4.5 times a £1,000 per day annualised income of £230,000, the maximum mortgage is £1,035,000. With specialist lenders offering 5 times, this rises to £1,150,000.
For high-earning IT contractors, lender selection becomes even more critical. Not all specialist contractor lenders operate comfortably at loan sizes above £750,000 to £1 million. We work with lenders experienced in high-value IT contractor lending and ensure your application is placed with the lender best equipped to deliver the result your income supports.
Some lenders will consider retained company profit alongside your day rate income, which can be beneficial if you have accumulated significant profit within the company. This approach is available from a smaller number of specialist lenders and requires different documentation — we assess whether it produces a better outcome than standard day rate annualisation for your specific situation.
Some IT contractors work on multiple engagements at the same time. Most lenders will use the higher or primary contract rate rather than combining multiple day rates. However, some specialist lenders will consider combined contract income where both engagements are documented and consistent. We identify which approach maximises your assessed income.
Umbrella workers receive PAYE payslips, but the best lenders for IT contractors will look at your assignment rate before umbrella deductions rather than just your take-home pay. This means an IT contractor on a £600 per day umbrella engagement should be assessed on £600 per day — not on the net amount after employer’s NI, holiday pay and umbrella margin.