
Locum doctors across all specialities — GPs, consultants, SHOs and registrars — earn strong incomes, yet variable pay from multiple sources is frequently mishandled by mainstream lenders. We place locum doctor mortgages with lenders who understand healthcare professional income and assess it correctly.
Locum doctors often earn through a combination of sessions, agency work, hospital shifts and private practice. Specialist lenders understand these income structures and apply assessment methods designed for medical professionals.
Lenders assess locum earnings based on actual working patterns, session rates and documented income history.
GMC registration can provide access to specialist mortgage products designed for qualified healthcare professionals.
Income from sessions, daily rates and agency assignments can be assessed using methods that reflect real earning capacity.
Specialist lenders understand the unique income structures of GPs, consultants and hospital locums.
GP locums working through a limited company or as self-employed practitioners are assessed on their average sessional income. A GP locum working five sessions per week at £450 per session has a weekly income of £2,250 and an annualised income of approximately £103,500 — a figure that supports a competitive mortgage with the right lender.
For GP locums who have recently left a salaried GP position, the transition from employed to locum income means the most recent six to twelve months of locum earnings are the primary evidence base. We identify lenders willing to use recent locum income alongside prior employed income history.
Many locum doctors work across multiple agencies, NHS trusts and private healthcare providers. The right lender can assess these income streams together rather than viewing them separately.
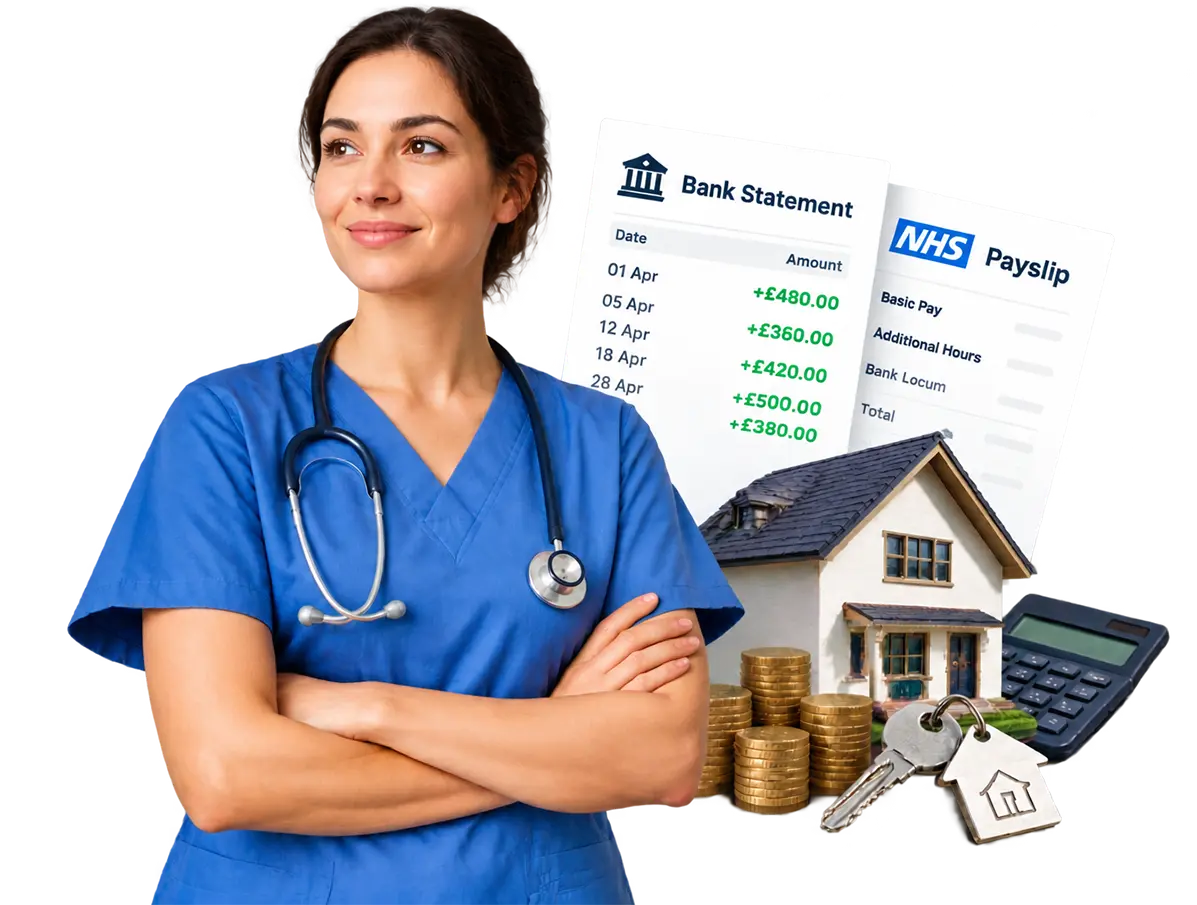
Junior doctors working as NHS bank locums or on trust grades alongside their training receive income that varies with the shifts booked. For mortgage purposes, lenders assess the average monthly earnings from bank statements rather than assuming a fixed monthly income.
The combination of training salary (if any) and bank locum income is assessed by most lenders as combined employment and supplementary income. We identify the lenders whose criteria best accommodates this combination.
Locum consultants and doctors who also carry out private practice — privately referred outpatient consultations, private surgical lists, cosmetic procedures — have additional income that some lenders will include alongside NHS locum earnings. Consistent private practice income over twelve or more months is assessable by specialist lenders.
Yes — GMC-registered doctors qualify for professional mortgage products at a number of lenders, offering enhanced income multiples of 5 to 5.5 times. For a locum consultant on high earnings, this can add hundreds of thousands to the available mortgage. We always check professional product eligibility for doctor clients.
Yes — specialist healthcare lenders will consider income from multiple agencies, averaged over three to twelve months. The key is providing payslips or payment records from each agency alongside bank statements confirming the deposits.
Variable income is the norm for locum doctors and specialist lenders are comfortable with it. They average your income over three to twelve months rather than requiring consistent monthly figures. We identify the lenders whose averaging methodology gives you the best assessed income.
For professional mortgage products available to GMC-registered doctors, some lenders will consider recent-to-locuming applicants with as little as three to six months of locum income history, where the applicant has a strong prior employed medical career. Standard contractor lenders typically require twelve months. We advise on the most appropriate approach for your specific history.
Supplementary medical income from writing, expert witness or medico-legal work can be included by some lenders if it is consistent and documented. It is treated as supplementary income alongside the primary locum income.