
Locum consultants combining NHS sessions and private practice can earn £300,000 to £500,000 or more annually, yet few mainstream lenders understand how that income is structured. We place locum consultant mortgages with specialist lenders who assess NHS tariff income and private practice billing together, producing an offer that reflects true earning capacity.
NHS locum consultants often earn through a combination of trust bookings, agency placements and specialist clinical work. Specialist lenders understand these income structures and assess them using methods designed for senior medical professionals.
Income is assessed using documented NHS locum earnings and established consultant working patterns.
Regular locum sessions and ongoing trust engagements help demonstrate sustainable earning capacity.
Senior consultant earnings can support substantial borrowing when assessed by the right lender.
Lenders experienced with consultant-level applicants understand the realities of NHS locum work.
Private practice income for consultants comes from direct patient consultations, surgical lists, diagnostic procedures and insurance-referred work. The income is typically self-employed in nature and varies with activity levels, referral patterns and practice profile.
Consistent private practice income over two or more years is assessable by most specialist lenders. Some lenders will accept one year of private practice income for consultants who have recently moved into private practice from a salaried NHS post. The income is evidenced through SA302s and accounting records.
Professional mortgage products recognise the qualifications and earning potential of GMC-registered consultants, often providing greater borrowing flexibility.
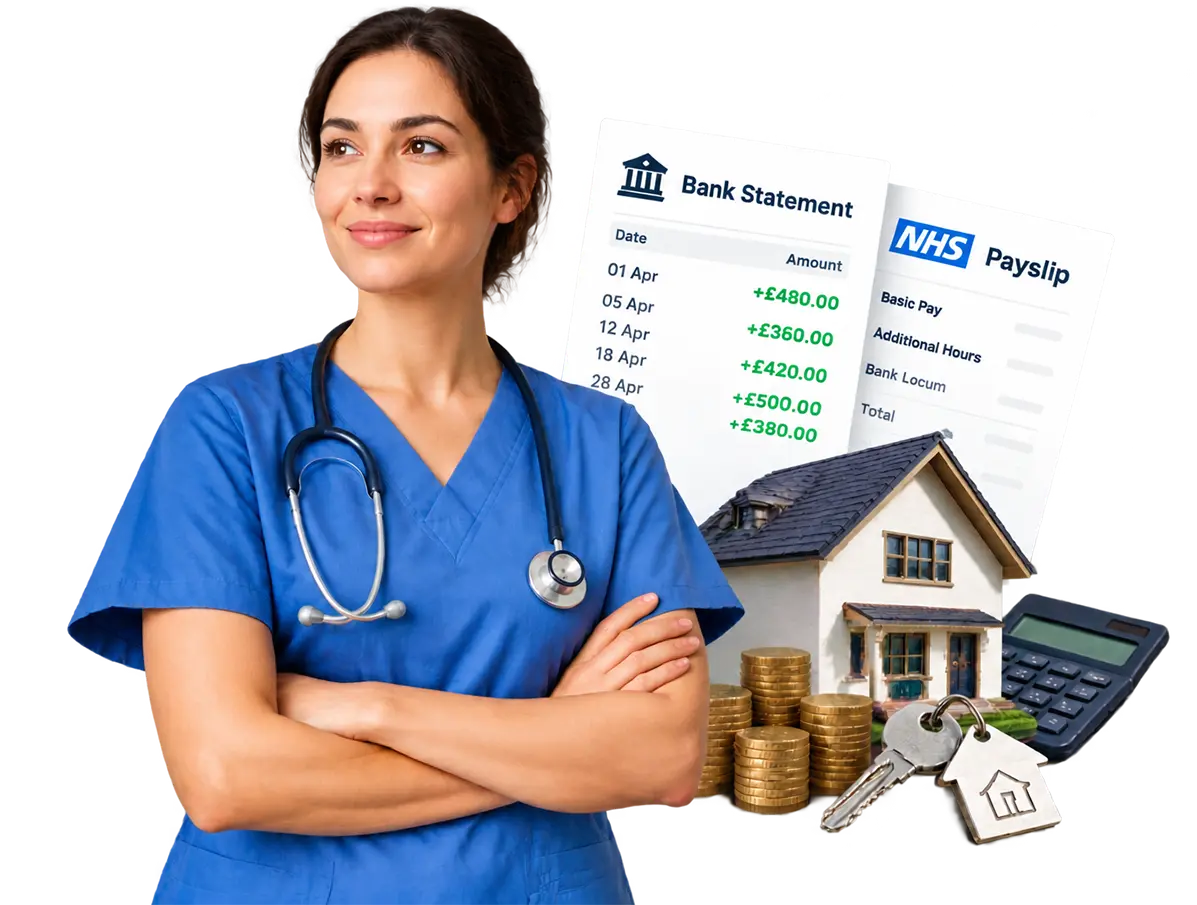
Many locum consultants combine NHS agency work with private practice some days in NHS trusts, some in private hospitals or clinics. This combined income picture is straightforward for specialist healthcare lenders who are familiar with consultant working patterns.
We identify the lenders best equipped to assess combined NHS locum and private practice income and ensure both components are included in the affordability calculation.
Senior consultants approaching retirement or considering reducing their NHS commitment may have complex pension positions NHS pension combined with personal pension contributions, AVCs and potentially a defined contribution pension alongside the defined benefit NHS scheme.
For consultants planning to reduce their working hours or transition to retirement, we advise on equity release, retirement interest-only mortgages and later life products alongside standard residential mortgages, ensuring the right solution for each stage of the career.
Yes — specialist healthcare lenders will consider combined NHS and private income. The NHS income is typically averaged from bank statements; the private income is evidenced through SA302s or accountant’s certificates. Together they produce the most accurate picture of your earning capacity.
Your medical specialty does not directly affect which mortgage products you can access. However, specialty-specific income levels vary — a locum anaesthetist or radiologist may earn significantly more than a locum in a lower-demand specialty — and the resulting day rate or sessional rate determines the mortgage available.
A recent transition from substantive post to locum is common and understood by specialist lenders. If you have at least six months of locum income history, most specialist healthcare lenders will consider your application. Professional mortgage products may be accessible from the outset of your locum career given your GMC registration.
The maximum depends on your specific earnings and circumstances. For a consultant earning £300,000 annually, at 5 times income with a professional lender that is £1,500,000. We provide a precise figure based on your income documentation and full circumstances.
Your NHS pension is an asset and a future income stream but is not typically included in current affordability assessments for a standard mortgage. For later life mortgages and equity release, pension income in payment is included. For retirement interest-only products, pension income may be the primary income source used.