
Locum dentists and pharmacists face shared mortgage challenges — variable income across multiple practices or pharmacies, mixed NHS and private work, and GDC or GPhC registration that most generalist brokers don't know how to leverage.
We place these mortgages with specialist lenders who understand sessional income, multiple-source earnings, and the enhanced consideration that qualified dental and pharmacy professionals deserve.
Dental professionals often earn through a mix of NHS contracts, private treatments and sessional work. Specialist lenders understand these income structures and assess them in a way that reflects real professional earning potential.
Income from NHS, private and session-based dental work can be assessed as part of a complete earnings profile.
Lenders familiar with the dental sector understand how UDA-based and private income models operate.
Mortgage affordability should reflect current professional income rather than simplified historic figures.
Working with lenders experienced in dental careers can lead to stronger borrowing outcomes.
Locum pharmacists are typically paid on a daily or hourly rate by pharmacies or agencies. Day rates for locum pharmacists range from £180 to £280 per day for standard community pharmacy work, with higher rates for specialist or urgent-need placements.
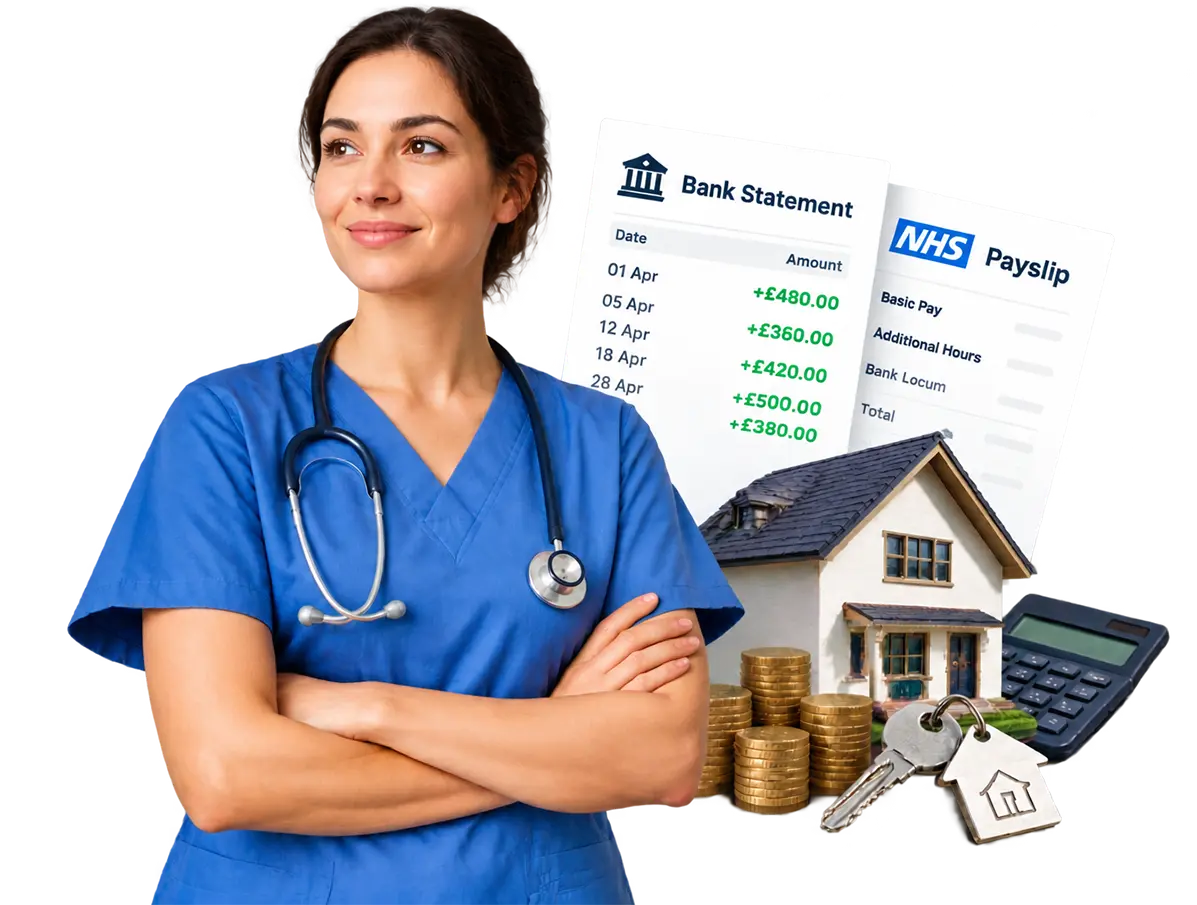
Pharmacist locum income is assessed by specialist lenders using averaged monthly earnings from bank statements and payslips. For GPhC-registered pharmacists, professional mortgage products with enhanced multiples may be available.
Professional registration demonstrates recognised qualifications, regulatory standards and long-term career stability, all of which can strengthen a mortgage application.
Associate dentists working under NHS contracts are paid on a UDA basis — a payment per unit of activity completed. UDA income varies with activity levels and the BDA scale of fees. For mortgage purposes, associate dentist income is typically assessed using two years of SA302s for established associates, or averaged monthly income for more recent associates.
The NHS performer number and list of approved practices provides useful evidence of professional standing and the established nature of the dental career.
Some locum dentists and pharmacists own a practice or pharmacy alongside their locum work. Practice or business ownership income introduces complexity — the mortgage assessment needs to consider both the locum income and the business income in the most beneficial way.
We assess the full picture and advise on the most beneficial lender and assessment method for combined locum and business owner income.
Yes — GDC-registered dentists qualify for professional mortgage products at certain lenders, with enhanced income multiples of 5 to 5.5 times. We always check professional product eligibility for dental professionals and compare against standard products.
Variable UDA income is assessed by averaging your earnings over the most recent twelve months. Lenders look at the overall annual income level rather than requiring consistent monthly figures. Two years of SA302s is the standard requirement for established associate dentists.
Yes — combined income from multiple pharmacy agencies is assessed by specialist lenders using averaged bank statement income. We confirm the specific methodology of each lender we recommend.
Yes — most specialist dental lenders will assess combined NHS and private income. The NHS element is evidenced through performer number records and SA302s; the private element through practice accounts and bank statements.
Professional mortgage products from certain lenders are available to newly qualified GDC and GPhC registrants, reflecting the strong and consistent earning trajectory of dental and pharmacy professionals. The specific requirements vary by lender — we identify the most appropriate options for your career stage.